Friday, 3 August 2012

"Oil And Gold Seasonals Suggest BTFD"

Brent Crude's two major bullish seasonals...


and Gold's three periods of bullish seasonality...


Quote & images : Zerohedge


Gold margins getting tight, says Gold Fields chief

The wave of rationalisation that is starting to emerge among the major diversified miners will soon spread to the gold sector, as soaring costs and labour shortages begin to squeeze margins.
That warning from Nick Holland, the head of South African miner Gold Fields Limited, came this afternoon as the world's fourth biggest gold company addressed the Melbourne Mining Club.
Mr Holland criticised fellow gold producers for failing to include corporate and capital costs when publicising their profit margins, saying they were only fooling themselves and governments, who would duly seek to tap the industry for more taxes.
Mr Holland said rising energy, labour and production costs would virtually double costs in the next five years, and a gold price of close to $US2000 per ounce would be needed to keep pace

If costs remain close to $US1600 where they have been in recent weeks, much of the industry would be "killed", he said, and many companies would have to pull back on projects.
"It may be that we have are going to have to see the sector rationalise before people believe us," he said.
Mr Holland said gold companies would have to start favouring dividends and returns to shareholders over marginal production if it is to win back investors, who have fled to gold-focused exchange traded funds in recent years.
Gold Fields is based in Johannesburg but operates the St Ives mine in Western Australia, and Mr Holland said he was looking for another mine in Australia.
Mr Holland said margins at St Ives were "tight" and the company would have to work hard to sustain that mine.

http://www.smh.com.au/business/mining-and-resources/gold-margins-getting-tight-says-gold-fields-chief-20120731-23cal.html

For similar articles :

WWW.PRECIOUS-METAL-INVESTMENT.BLOGSPOT.CO.UK

Saturday, 7 July 2012

Revealed: why Gordon Brown sold Britain's gold at a knock-down price


A great deal of Gordon Brown’s economic strategy would strike a sane man as troubling. Not a great deal was mysterious. The orgy of consumption spending, frequent extensions of the cycle over which he would “borrow to invest”, proclamations of the “end of boom and bust”: these are part of the armoury of modern politicians, of all political hues.
One decision stands out as downright bizarre, however: the sale of the majority of Britain’s gold reserves for prices between $256 and $296 an ounce, only to watch it soar so far as $1,615 per ounce today.
When Brown decided to dispose of almost 400 tonnes of gold between 1999 and 2002, he did two distinctly odd things.
First, he broke with convention and announced the sale well in advance, giving the market notice that it was shortly to be flooded and forcing down the spot price. This was apparently done in the interests of “open government”, but had the effect of sending the spot price of gold to a 20-year low, as implied by basic supply and demand theory.
Second, the Treasury elected to sell its gold via auction. Again, this broke with the standard model. The price of gold was usually determined at a morning and afternoon "fix" between representatives of big banks whose network of smaller bank clients and private orders allowed them to determine the exact price at which demand met with supply.
The auction system again frequently achieved a lower price than the equivalent fix price. The first auction saw an auction price of $10c less per ounce than was achieved at the morning fix. It also acted to depress the price of the afternoon fix which fell by nearly $4.
It seemed almost as if the Treasury was trying to achieve the lowest price possible for the public’s gold. It was.
One of the most popular trading plays of the late 1990s was the carry trade, particularly the gold carry trade.
In this a bank would borrow gold from another financial institution for a set period, and pay a token sum relative to the overall value of that gold for the privilege.
Once control of the gold had been passed over, the bank would then immediately sell it for its full market value. The proceeds would be invested in an alternative product which was predicted to generate a better return over the period than gold which was enduring a spell of relative price stability, even decline.
At the end of the allotted period, the bank would sell its investment and use the proceeds to buy back the amount of gold it had originally borrowed. This gold would be returned to the lender. The borrowing bank would trouser the difference between the two prices.
This plan worked brilliantly when gold fell and the other asset – for the bank at the heart of this case, yen-backed securities – rose. When the prices moved the other way, the banks were in trouble.
This is what had happened on an enormous scale by early 1999. One globally significant US bank in particular is understood to have been heavily short on two tonnes of gold, enough to call into question its solvency if redemption occurred at the prevailing price.
Goldman Sachs, which is not understood to have been significantly short on gold itself, is rumoured to have approached the Treasury to explain the situation through its then head of commodities Gavyn Davies, later chairman of the BBC and married to Sue Nye who ran Brown’s private office.
Faced with the prospect of a global collapse in the banking system, the Chancellor took the decision to bail out the banks by dumping Britain’s gold, forcing the price down and allowing the banks to buy back gold at a profit, thus meeting their borrowing obligations.
I spoke with Peter Hambro, chairman of Petroplavosk and a leading figure in the London gold market, late last year and asked him about the rumours above.
“I think that Mr Brown found himself in a terrible position,” he said.
“He was facing a problem that was a world scale problem where a number of financial institutions had become voluntarily short of gold to the extent that it was threatening the stability of the financial system and it was obvious that something had to be done.”
While the market manipulation which occurred when the gold reserves were sold was not illegal as the abuse at Barclays may have been, the moral atmosphere in which it took place was identical.
The crash which began in 2007 and endures still was the result of an abdication of responsibility across the financial sector. This abdication ranged from the consumer whose thirst for goods pushed him beyond into grave debt to a government whose lust for popularity encouraged it to do the same.
Responsibility is evaded by all bar those on whose shoulders it ought to rest. The gold panic of 1999 was expensively paid for by the British public. The one thing politicians ought to have bought with that money was a lesson in the structural restraints which needed to be placed on banks now that the principle that they were ultimately public liabilities had been established.
It was a lesson which could have acted to restrain all players in the credit market boom of the 2000s. It was a lesson which nobody learnt.

http://blogs.telegraph.co.uk/finance/thomaspascoe/100018367/revealed-why-gordon-brown-sold-britains-gold-at-a-knock-down-price/#disqus_thread

Wednesday, 23 May 2012

Chart of the week: China, India & gold


High quality global journalism requires investment. Please share this article with others using the link below, do not cut & paste the article. See our Ts&Cs and Copyright Policy for more detail. Email ftsales.support@ft.com to buy additional rights. http://blogs.ft.com/beyond-brics/2012/05/21/chart-of-the-week-china-india-gold/#ixzz1vlQzAFeL

There comes a time in the life cycle of most commodities when China takes over in terms of demand. For gold, long the preserve of India, that moment is nearly upon us.
Data from the World Gold Council and compiled by beyondbrics show that Chinese demand for gold, both in terms of jewellery and investment, has overtaken India on a quarterly basis. On a rolling four-quarters, China is just – just – behind India. The chart below shows the rolling total, and the pattern is clear.

High quality global journalism requires investment. Please share this article with others using the link below, do not cut & paste the article. See our Ts&Cs and Copyright Policy for more detail. Email ftsales.support@ft.com to buy additional rights. http://blogs.ft.com/beyond-brics/2012/05/21/chart-of-the-week-china-india-gold/#ixzz1vlR2m7pW
In 2011 China’s gold purchases totalled 769.8 tonnes, compared to India’s 933.4 tonnes. But the reduction in demand from India may see a drop under 900 tonnes for 2012, and China surge to over 900 tonnes.
Overall, gold demand is down – around 5 per cent from 1,150.7 tonnes in Q1 2011 to 1,097.6 tonnes in the same 2012 period. China and India together make 42 per cent of the world total.
The World Gold Council had this on India:

High quality global journalism requires investment. Please share this article with others using the link below, do not cut & paste the article. See our Ts&Cs and Copyright Policy for more detail. Email ftsales.support@ft.com to buy additional rights. http://blogs.ft.com/beyond-brics/2012/05/21/chart-of-the-week-china-india-gold/#ixzz1vlR5vbLP
Gold demand in India was affected in Q1 2012 by a number of factors; a new tax on gold jewellery, two increases in the import duty for gold and weakness and volatility in the rupee. Jewellery demand fell 19% to 152.0t from Q1 2011. Investment demand was down 46% from the previous year at 55.6t. In May, the government withdrew the new tax on jewellery and the market is already responding positively.

But China is set to take the lead:
High quality global journalism requires investment. Please share this article with others using the link below, do not cut & paste the article. See our Ts&Cs and Copyright Policy for more detail. Email ftsales.support@ft.com to buy additional rights. http://blogs.ft.com/beyond-brics/2012/05/21/chart-of-the-week-china-india-gold/#ixzz1vlRPHjZk
China and India have seen continuing economic growth and whilst China’s economy is expected to slow, it will nonetheless surpass the rates of growth in the West. As we previously forecast it is likely China will become the largest source of demand for gold in 2012.

http://blogs.ft.com/beyond-brics/2012/05/21/chart-of-the-week-china-india-gold/#axzz1vlQUiUUQ

Sunday, 22 April 2012

Buying gold at discount

Buying gold at discount 


China has been trying to diversify her foreign exchange reserves for some time. We are all familiar with the figures released by the likes of the World Gold Council about Chinese gold investment demand, as well as statistics showing official gold imports through Hong Kong into the Chinese mainland. Chinese reserves contain only 2% gold, compared to nearly 10% for India and Russia, and figures in the 70th percentile for developed nations such as the USA and Germany.
China is getting out of paper and into gold as fast as she can, because she simply doesn't have enough of old yella'. Any effort to internationalise the RMB will not work until it is a trusted enough currency. One of the key ways to achieve trust is larger gold reserves.
It is not just the PBOC that is on the gold rush, since opening up the domestic gold market individuals are also allowed to invest in gold. The Chinese still have a limited range of savings and investment options open to them (one of the reasons why so much money flowed into their property bubble), and gold continues to shine when other investment options (especially the Chinese stock market) are being questioned.
Gold above ground
However the physical gold market is not a deep and liquid market like the US treasury market. Therefore China is not able to rebalance her portfolio out of sovereign debt quickly without causing the gold price to ‘gap up’ whilst sending ripples through the gold market.
The Chinese authorities have even urged caution about taking up the IMF’s remaining gold. In early 2010 a senior official from the China Gold Association was quoted by Reuters: “It is not feasible for China to buy the IMF bullion, as any purchase or even intent to do so would trigger market speculation and volatility.”
China knows that she must tread carefully in the physical gold market, for fear of her bidding power sending the price upwards before she has been able to accumulate enough gold in the PBOC’s coffers. China does not want to be chasing the gold price.
For this reason she is very happy to watch current weakness whilst apparently keeping bids in the market at the $1,500, $1,550, and $1,600 level.
Nonetheless China is accumulating physical gold, often via her Sovereign Wealth Funds, and other proxies, so that her bids are not open for all to see. Large above ground inventories of physical bullion are difficult to find outside of central bank vaults (even when they do keep it inside their own borders), or even at a smaller scale the ETFs, and COMEX inventories.
Gold in the ground
Where can China turn to firstly get her hands on more gold, but secondly without sending the gold price soaring?
The answer is increasingly being found in gold mining.
By buying gold mines, and thus accumulating the produced gold before it hits the international market, China is able to purchase gold below the spot gold price. China is just taking on the mining risk to do so.


http://www.stockopedia.co.uk/content/buying-gold-at-discount-65444/


http://precious-metal-investment.blogspot.co.uk/

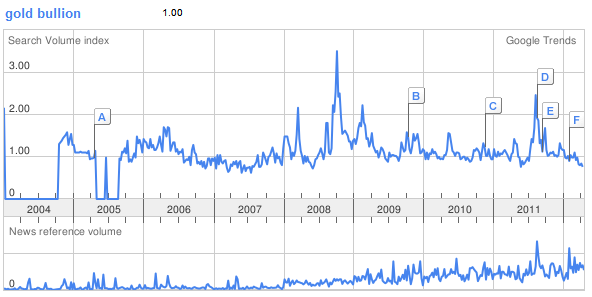
Google search activity since 2004 for "Gold bullion"


The global search Gold Bullion has dipped towards the end of 2011 but the news reference volume is slowly increasing.